For many businesses, tax becomes a priority when a filing deadline approaches. Finance teams begin gathering documents, reviewing transactions and reconciling accounts while managing their usual responsibilities.
Although meeting deadlines is essential, waiting until the last minute can leave little time to address missing records, identify errors or understand the financial implications of business decisions. A more effective approach is to make tax planning part of regular financial management.
Tax obligations are influenced by everyday business activities. Hiring employees, entering into contracts, purchasing assets, expanding into new markets or restructuring operations can all have tax implications.
When these decisions are made without considering the potential consequences, businesses may face unexpected liabilities, cash flow pressures or compliance challenges.
Maintaining accurate records throughout the year is one of the simplest ways to improve tax preparedness. Missing invoices, incomplete documentation and unreconciled accounts can complicate the preparation of returns and make it harder to establish whether transactions have been treated correctly.
Tax planning also supports better cash flow management. A business may be profitable but have limited cash available because funds are tied up in unpaid invoices, inventory or operating expenses. If anticipated tax payments are not included in financial forecasts, meeting those obligations may become difficult. Regular reviews help management plan for payments rather than treating them as unexpected expenses.
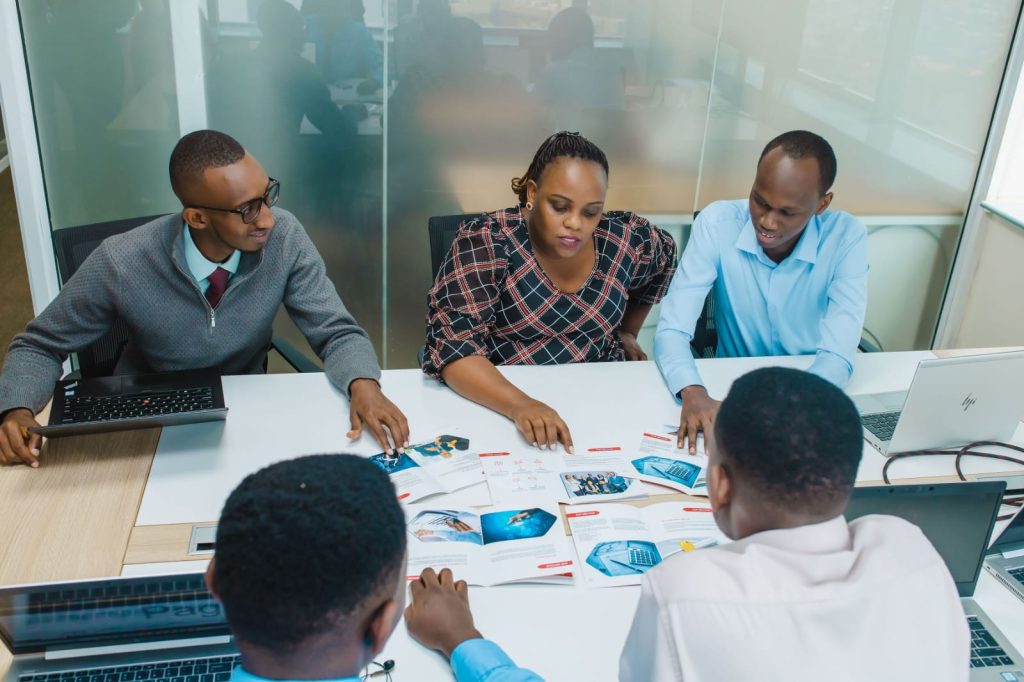
Early planning is particularly valuable when making significant business decisions. A company considering an acquisition, restructuring its operations or entering a new market may need to assess the relevant tax implications before proceeding. Obtaining professional advice at the right time allows management to understand its obligations and evaluate the financial consequences of different options.
How Can Businesses Make Tax Planning Part of Their Routine?
Tax planning does not need to be a separate, complicated exercise. Businesses can integrate it into existing financial management practices by maintaining organised records, reviewing their applicable obligations and monitoring relevant filing and payment deadlines.
Tax should also be considered when preparing budgets and cash flow forecasts. As the business takes on new contracts, makes investments or changes its operating model, management should assess whether these developments affect its tax position.
Regular reviews can help identify inconsistencies between accounting records and tax declarations, incomplete supporting documents or transactions that may require further assessment. Addressing these issues early gives the business more time to investigate and seek appropriate guidance.
For businesses operating in Rwanda, staying informed about relevant Rwanda Revenue Authority requirements is also essential. Tax obligations vary according to the business’s circumstances, so current regulations and individual requirements should be confirmed before making decisions.
Tax planning does not eliminate legitimate tax obligations. Rather, it helps businesses understand and meet those obligations while considering tax implications as part of wider financial and strategic decisions.
Tax deadlines are predictable, but the work required to meet them happens throughout the year. Making tax planning part of everyday business management helps organisations prepare more effectively, manage financial commitments and reduce the pressure of last-minute compliance.